Numbers That Mean Money
A friend once showed me his betting slip and asked why his 66/1 golf bet paid less than he expected. He had backed a player each-way, did not understand what 1/5 odds meant on the place part, and was genuinely confused by the settlement. That conversation reminded me that odds — the fundamental language of betting — are a barrier for many golf punters, and misreading them costs real money on every single bet.
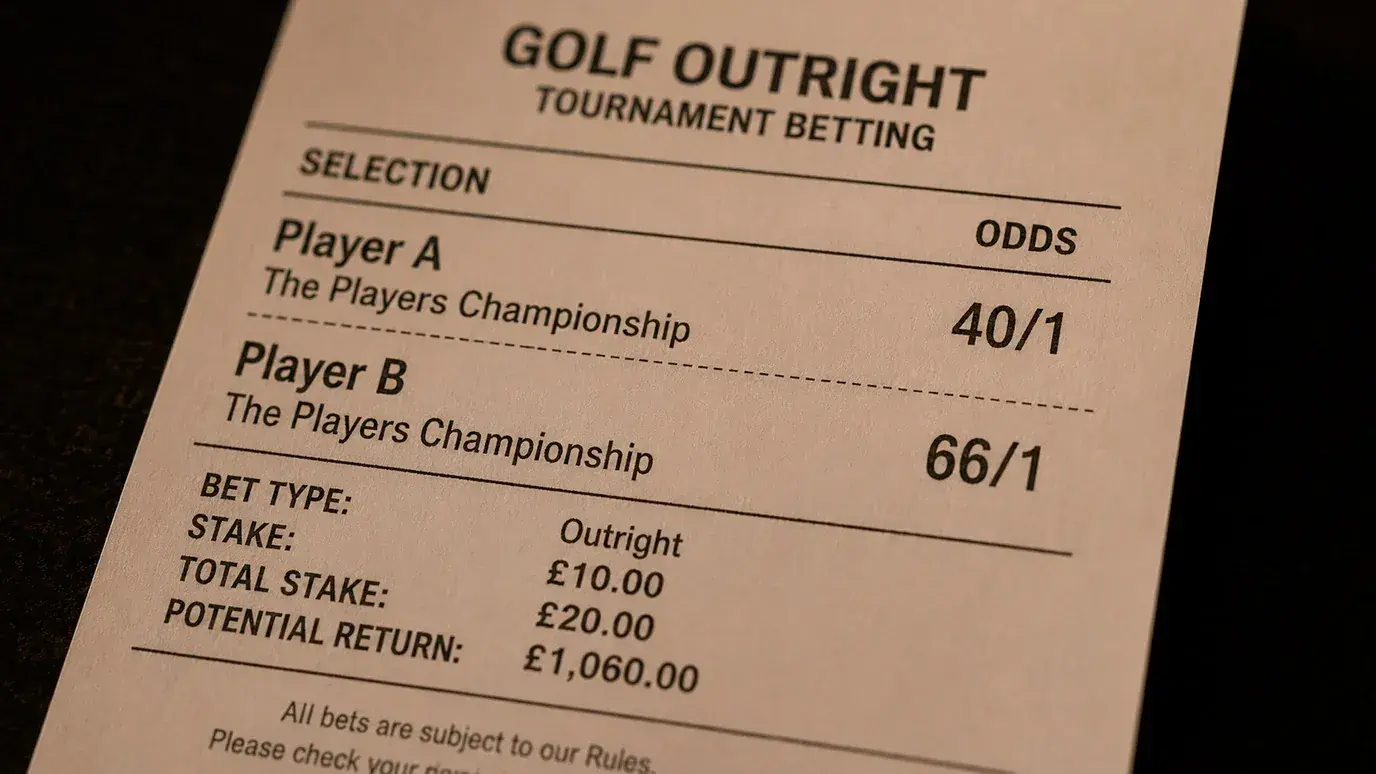
Golf odds are structurally different from those in most other sports. With outright markets accounting for 95% of UK golf wagering volume, the prices punters encounter regularly sit in the 10/1 to 200/1 range — far longer than the 1/2 to 5/1 prices that dominate football betting. Those long odds carry different mathematical properties, different relationships to probability, and different implications for bankroll management. Understanding them is not academic — it is the prerequisite for every other skill in golf betting.
This article covers fractional and decimal formats, the conversion to implied probability, and how the bookmaker’s margin inflates every price in the market.
Fractional Versus Decimal Odds
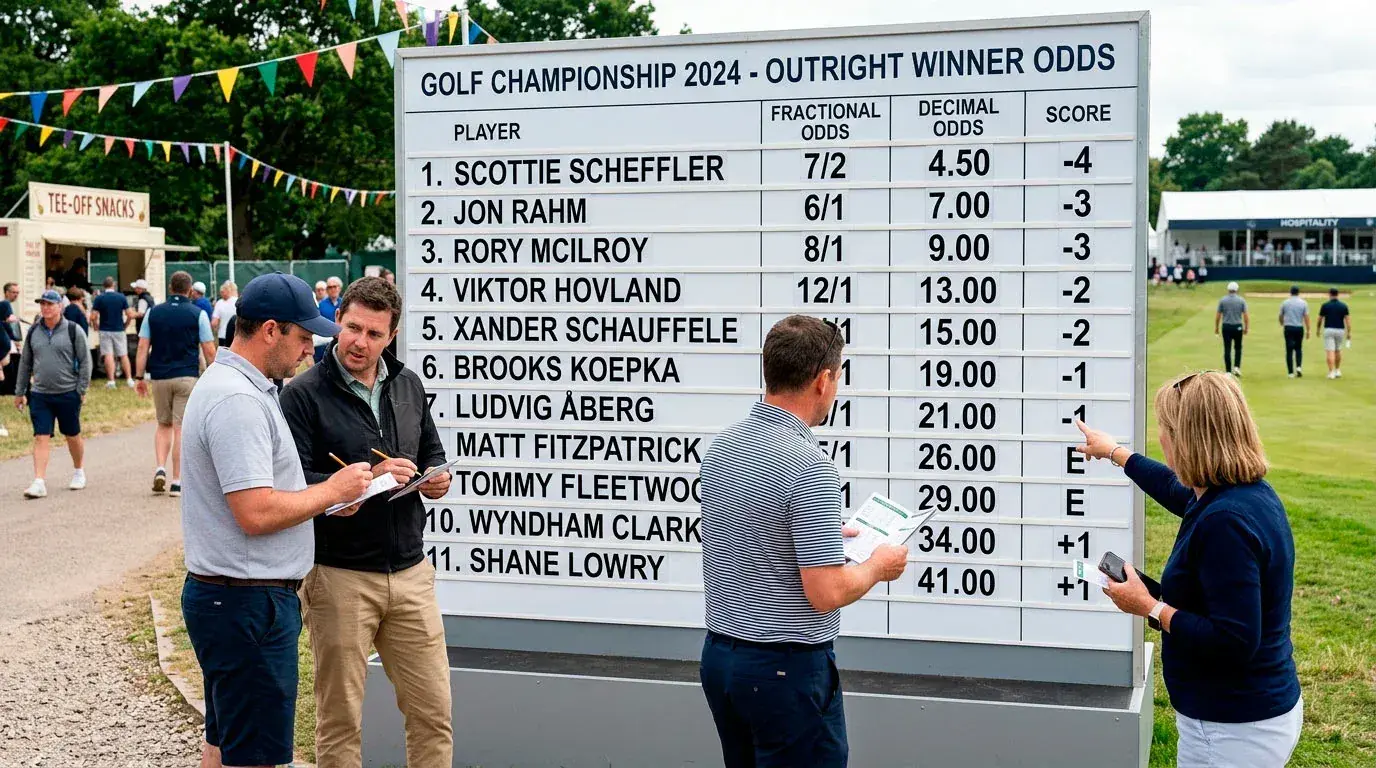
UK bookmakers traditionally display golf odds in fractional format: 40/1, 66/1, 150/1. The first number represents the profit relative to the second number, which is the stake. At 40/1, a GBP 1 bet returns GBP 40 profit plus your GBP 1 stake, for a total of GBP 41. Fractional odds are intuitive for simple prices but become awkward at non-standard fractions: 11/4, 100/30, 85/40. These require mental arithmetic that slows decision-making.
Decimal odds express the total return per unit staked, including the stake itself. The same 40/1 fractional price converts to 41.00 in decimal format. An 11/4 shot becomes 3.75 (11 divided by 4, plus 1). Decimal odds make comparison and calculation easier because every operation — probability conversion, expected value, payout calculation — requires a single division or multiplication rather than the two-step process fractional odds demand.
I switched to decimal format five years ago and have not looked back. The clarity is immediate: 41.00 is unambiguously larger than 35.00, whereas the fractional equivalents (40/1 vs 34/1) require a moment’s thought to confirm the relationship. For golf betting, where you are regularly comparing prices across multiple bookmakers and multiple players, that clarity compounds into a meaningful time saving.
The conversion between formats is straightforward. Fractional to decimal: divide the first number by the second, then add 1. So 66/1 becomes (66/1) + 1 = 67.00. Decimal to fractional: subtract 1, then express as a fraction. So 5.50 becomes 4.50/1, or 9/2 in simplified form. Most UK sportsbook apps allow you to toggle between formats in the settings, and I recommend setting decimal as your default if you plan to do any form of value calculation.
Implied Probability in Golf
Every set of odds contains hidden information: the bookmaker’s assessment of probability. Extracting that assessment — called implied probability — is the foundation of value betting, and it is where golf’s long odds create unique opportunities.
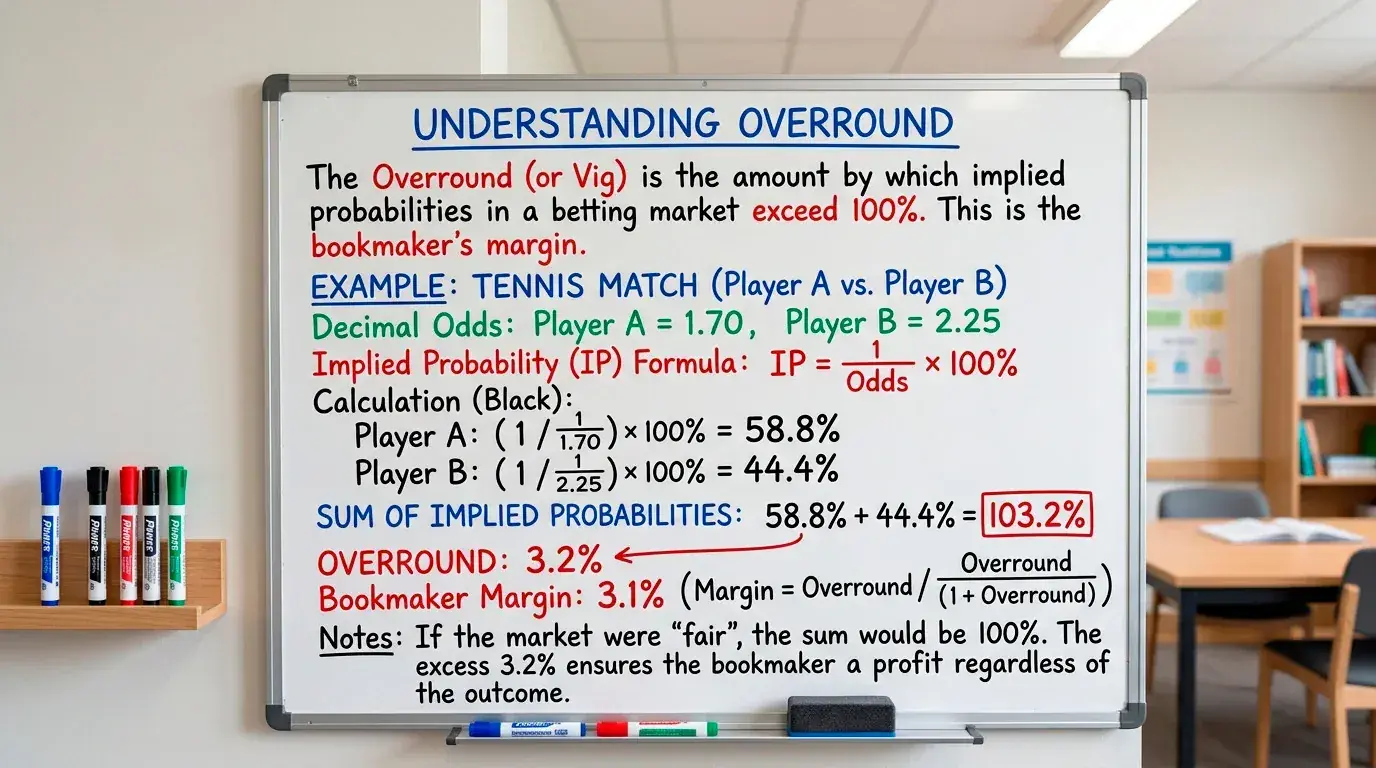
The formula is: Implied probability = 1 / Decimal odds x 100. A player priced at 41.00 (40/1) has an implied probability of 1/41 x 100 = 2.44%. A player at 11.00 (10/1) has an implied probability of 9.09%. These numbers represent the bookmaker’s estimate of each player’s chance of winning, but they are not true probabilities — they include the bookmaker’s margin.
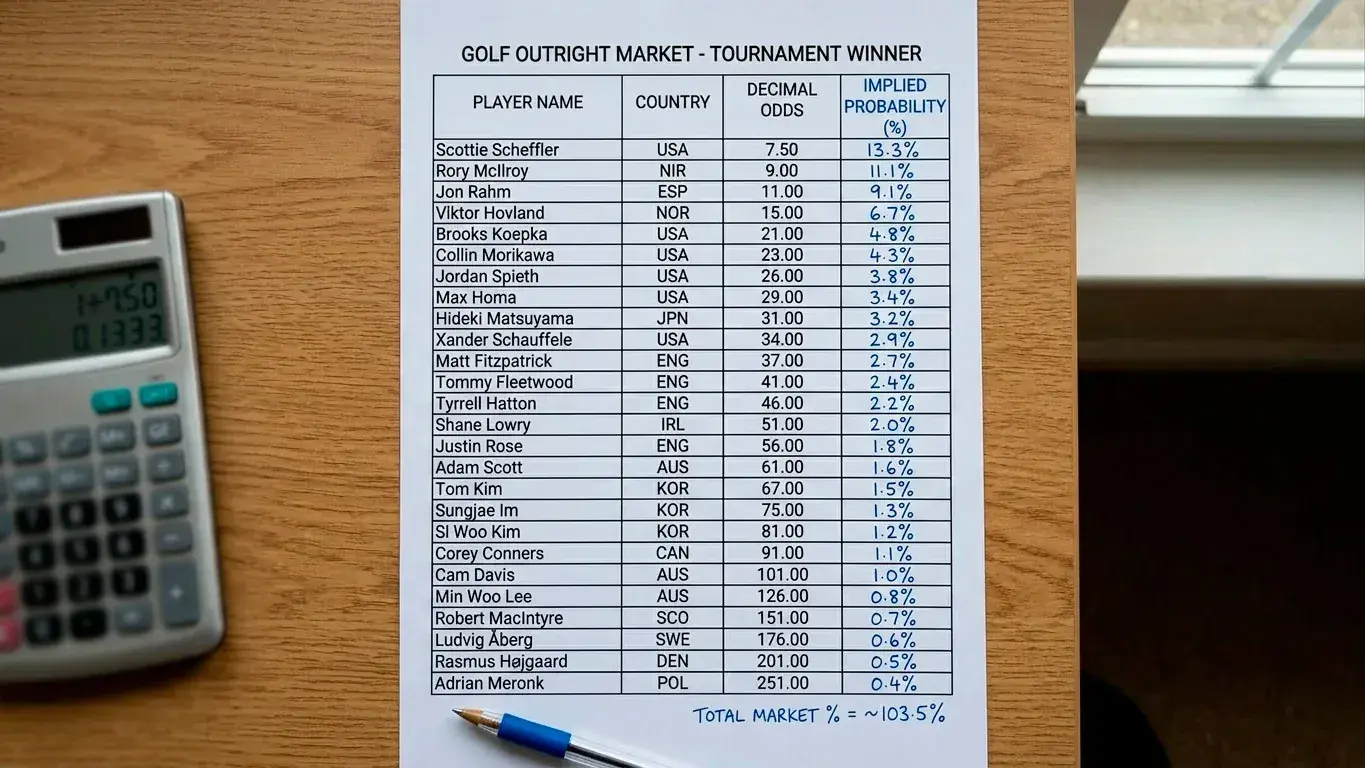
The average bookmaker win rate hit a record 9.7% in 2025, and that margin is embedded in every price. John Bushell, Managing Director of Sporting Insights, has noted the “continued rise in participation” in golf as a driver of industry growth. That participation growth feeds into wagering growth, which increases bookmaker revenue and allows operators to maintain or widen margins. For punters, the practical consequence is that the sum of implied probabilities across a full golf outright market significantly exceeds 100% — often reaching 130% to 150%. The excess above 100% is the overround, and it represents the collective tax that all punters pay.
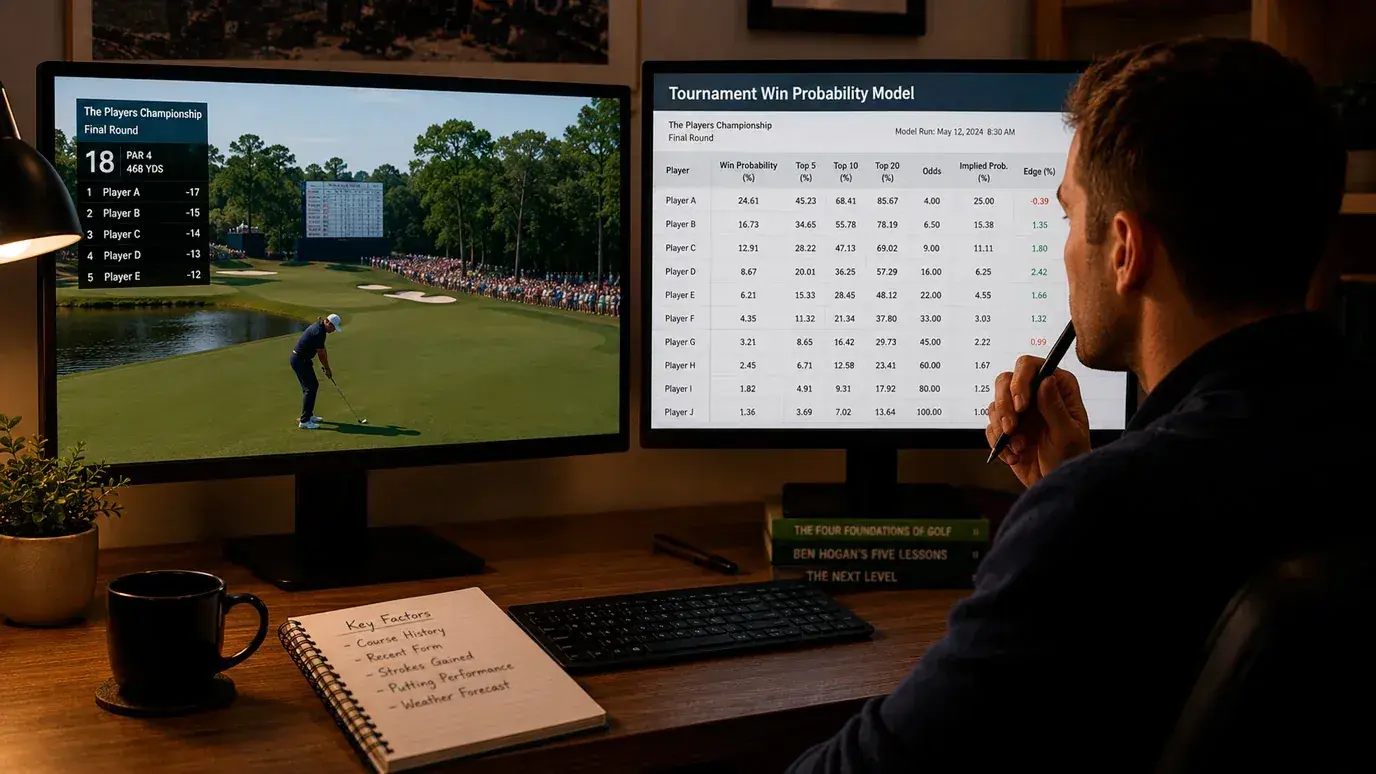
To find value, I compare my own probability estimate for a player against the bookmaker’s implied probability. If I estimate a player’s true win probability at 4% and the bookmaker’s implied probability is 2.5% (a 40/1 price), I have identified a value bet. The difference — 1.5 percentage points — is my estimated edge. Over hundreds of bets, consistently identifying these gaps is what separates profitable punters from the rest. The key insight for golf specifically is that the large overround in outright markets means even accurate probability estimates can find value, because the margin pushes many prices above their true probability levels. Smaller fields and shorter-odds markets have tighter overrounds and therefore less available value.
Overround and the Bookmaker’s Margin
The overround is the bookmaker’s built-in advantage, and understanding how it varies across golf markets is essential for allocating your betting activity efficiently.
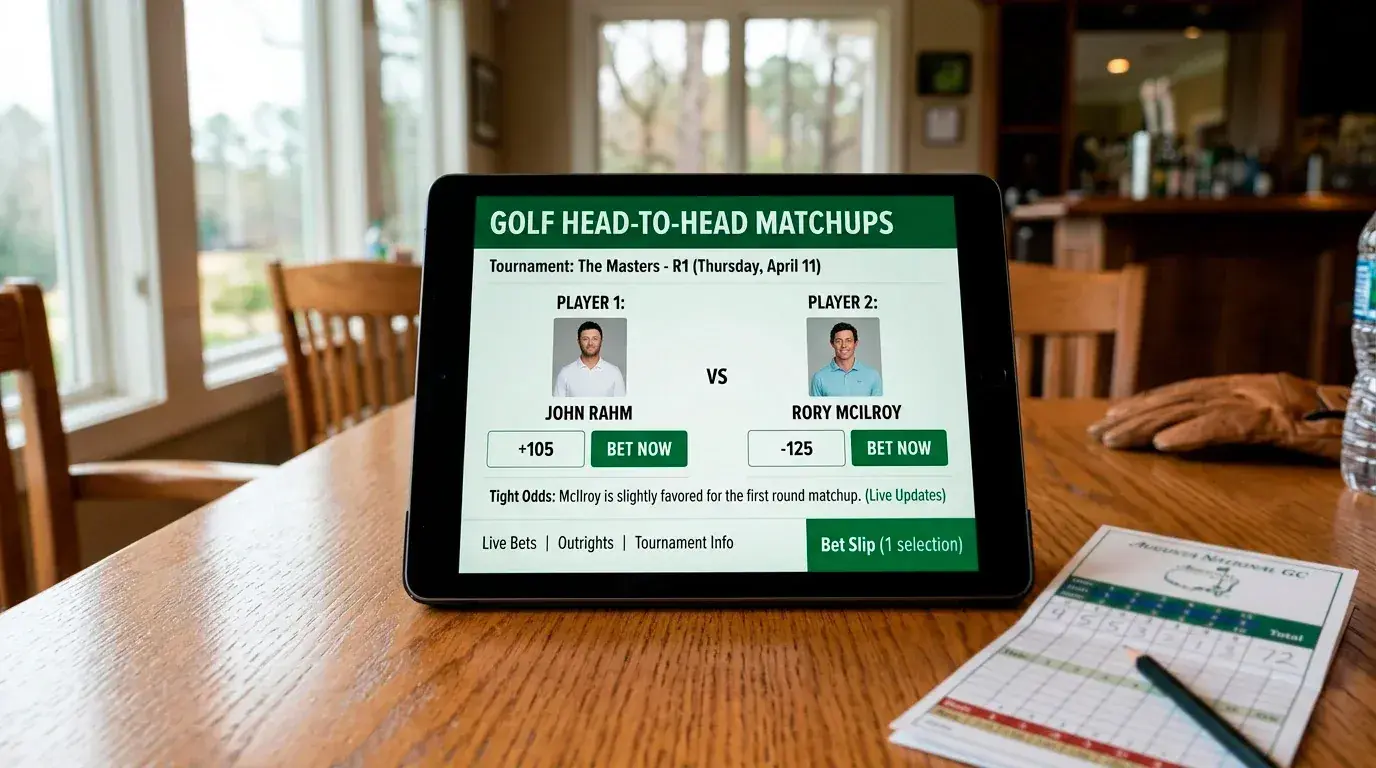
In a perfectly fair market, the sum of all implied probabilities would equal exactly 100%. In a real golf outright market with 150+ runners, the overround typically sits between 130% and 160%. That means for every GBP 1 wagered across the entire market, the bookmaker theoretically retains GBP 0.30 to GBP 0.60. The overround varies by market type: outright markets carry the highest overround because of the large number of runners; matchup markets sit at 107% to 115%; top-finish markets fall somewhere in between.
I calculate the overround for every market I bet into as a standard practice. The formula is: sum all implied probabilities (1/decimal odds x 100) for every selection in the market, then subtract 100. The result is the overround percentage. A 140% market has a 40% overround, meaning the bookmaker has embedded a 40% theoretical edge across the entire market.
For punters, the actionable takeaway is to focus activity on markets where the overround is lowest relative to your analytical edge. If your golf betting approach produces a 3% edge on outright markets with a 40% overround, your net position is negative — the market’s tax exceeds your skill advantage. But the same 3% edge applied to matchup markets with a 10% overround produces a positive net position. I allocate more capital to lower-overround markets and treat high-overround markets as occasional opportunities rather than primary betting venues.