A Different Product Entirely
The first LIV Golf event I attempted to bet on was a lesson in discovering how little infrastructure existed behind the headline names. I opened my usual three sportsbook apps, found an outright market on one, a partial matchup list on another, and nothing at all on the third. The field included multiple major champions, but the betting experience felt like wagering on a niche developmental tour. That gap between player quality and market depth defines the LIV Golf betting experience in 2026.
PGA Tour betting volume runs approximately 100 times higher than LIV Golf — a ratio that reflects not just audience size but the structural differences between the two products. LIV’s 54-hole, no-cut, shotgun-start format fundamentally changes how golf is consumed and, by extension, how it is priced. Golf remains the third most popular sport for betting in the UK, with 15% of active bettors placing golf wagers, but that audience has overwhelmingly oriented itself around PGA Tour scheduling and market availability.
This guide examines what LIV Golf betting actually looks like for UK punters: which markets exist, why volume remains so far below the PGA Tour, and what the format’s quirks mean for anyone considering a wager. For a look at European tour markets that sit between these two extremes, DP World Tour betting covers that middle ground.
LIV Format and Betting Impact
I spent a full season tracking LIV events specifically to understand how the format distorts conventional golf betting logic, and three differences stood out above everything else: the 54-hole structure, the shotgun start, and the absence of a cut.
Fifty-four holes instead of 72 compresses variance. In a standard 72-hole PGA Tour event, the cream generally rises — the best player’s advantage compounds over four rounds, and longshot winners are relatively rare. Over 54 holes, that compounding effect is weaker. A player who has a hot opening round carries a larger proportional advantage with only two rounds remaining. This means LIV outright markets should theoretically price frontrunners shorter and longshots slightly longer than equivalent 72-hole fields, but in practice the thin liquidity makes it difficult to assess whether the pricing actually reflects this.
Shotgun starts eliminate the wave advantage that matters so much in PGA Tour and Open Championship betting. At a traditional tournament, the morning wave might play in calm conditions while the afternoon wave battles afternoon winds — a draw bias that sharp punters exploit. LIV’s shotgun format puts everyone on the course simultaneously, equalising weather exposure across the field. This removes one of the most reliable analytical edges in golf betting and reduces the pre-tournament research to pure player-versus-player-versus-course analysis.
No cut means every player completes all 54 holes. In PGA Tour betting, the threat of a missed cut — a player finishing outside the top 65 and ties after 36 holes — shapes pricing for tail-end selections. A 150/1 longshot on the PGA Tour carries cut risk that suppresses their effective probability of winning. In LIV, that same calibre of player will definitely complete the tournament, which marginally increases their chance of a freak result but does not materially change their probability of winning against a 48-player field of elite professionals.
The team element adds a layer that has no PGA Tour equivalent. LIV features team competitions alongside the individual tournament, and some UK sportsbooks offer team winner markets. These are priced with wide margins due to limited historical data and the inherent difficulty of modelling three-or-four-player team performance in golf. The team market is an entertainment product, not an analytical one.
Volume Gap and Liquidity
The 100:1 volume disparity between PGA Tour and LIV Golf betting is not just a number — it is a structural reality that shapes every aspect of the LIV betting experience. Strategic partnerships between data companies and major sports organisations continue to deepen, with one major data provider noting accelerating momentum and growing demand from the world’s largest brands and agencies. But LIV’s data partnerships and commercial infrastructure remain less mature than the PGA Tour’s, and that immaturity flows directly into the betting markets.
Lower volume means wider margins. When a bookmaker prices a PGA Tour outright market, the competitive pressure from other operators, betting exchanges, and sharp money forces the overround down to 115-125% on a typical event. LIV outright markets routinely carry overrounds of 135-150%, reflecting both the thinner competition and the bookmaker’s reduced confidence in its own pricing. You are paying a higher tax on every LIV bet simply because the market is less efficient.
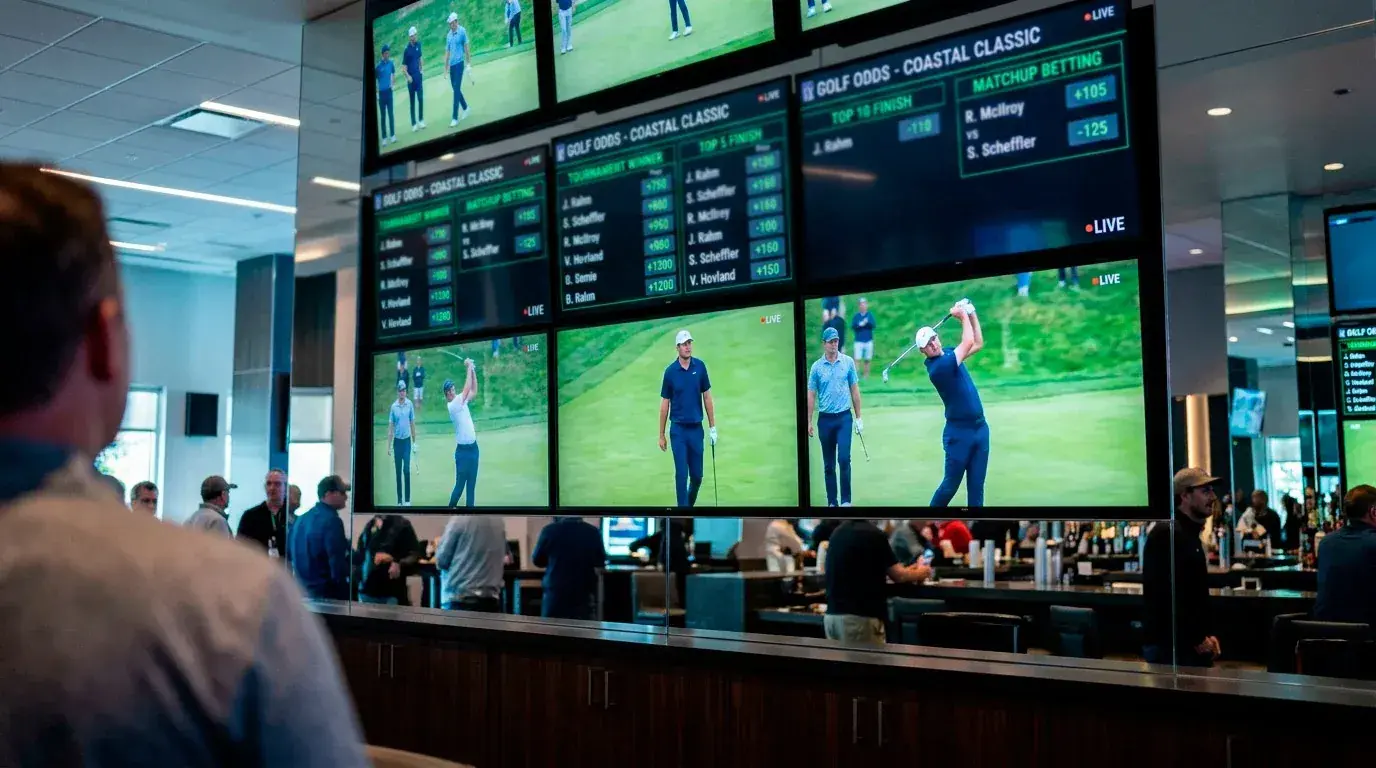
Matchup markets are severely limited. A PGA Tour event might generate 30-40 head-to-head matchups across major UK sportsbooks. A LIV event might produce five to ten, concentrated on the highest-profile players. If your analytical edge comes from identifying mismatched head-to-head prices — a core strategy for serious golf bettors — LIV simply does not provide enough matchups to build a portfolio.
Live betting availability is similarly constrained. The shotgun start means all 48 players are on the course simultaneously, which creates a data and pricing challenge that most sportsbooks handle by offering limited or no in-play markets for LIV events. PGA Tour in-play betting, by contrast, generates a continuous stream of updated prices from the first tee time to the final putt, with per-hole and per-group markets available on featured coverage. The live betting gap may be the single largest practical difference between the two products for engaged punters.
Integrity and Data Challenges
Golf betting integrity depends on robust monitoring infrastructure — data feeds that capture every shot, systems that flag unusual betting patterns, and regulatory frameworks that hold operators and players accountable. The PGA Tour has invested heavily in this area, integrating comprehensive monitoring solutions into its Integrity Program. LIV Golf has developed its own integrity protocols, but the independent verification and public reporting that characterise PGA Tour integrity efforts are less visible.
For UK punters, the practical concern is not match-fixing — the risk in golf at this level is extraordinarily low — but data reliability. PGA Tour ShotLink data feeds are the gold standard: every shot tracked by radar and laser, every distance measured, every lie recorded. This data feeds both the betting markets and the analytical models that punters use to assess those markets. LIV Golf does not have an equivalent public data system. The statistical information available for LIV events is thinner, less standardised, and harder to verify independently.
This data gap compounds the volume problem. Fewer bettors are comfortable wagering on events where the underlying data is less transparent, which suppresses volume, which keeps margins wide, which discourages more bettors — a self-reinforcing cycle. Until LIV Golf develops data infrastructure comparable to the PGA Tour’s, the betting markets around its events will remain structurally less attractive for punters whose approach depends on statistical analysis.
None of this means LIV Golf is unbettable. If you approach it as a smaller, less efficient market with specific format quirks — 54 holes, no cut, shotgun starts — rather than a direct substitute for PGA Tour wagering, there may be pockets of value precisely because the thin liquidity creates pricing errors that a thicker market would correct. The question is whether the wider margins and limited market range leave enough room for those errors to deliver net positive returns after the bookmaker’s additional tax.